ACE Money Transfer
ACE Money Transfer
14 Sep 2026
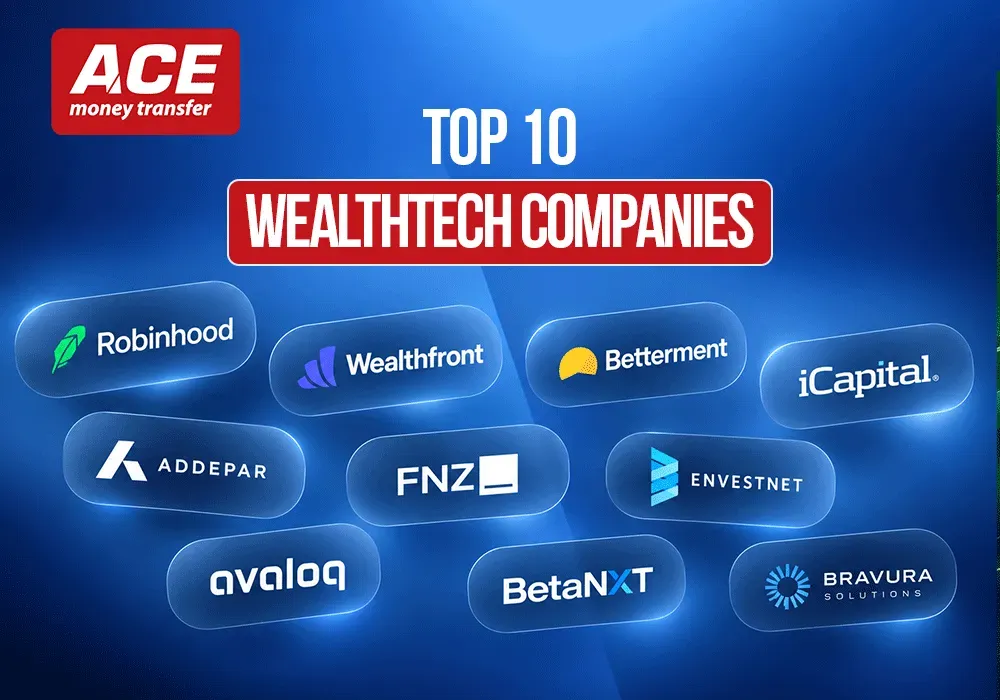
The wealthtech sector bridges traditional financial advisory with modern, scalable software-and in 2026, the transformation is accelerating. Across banks, advisory firms, and family offices, the top 10 wealthtech companies are rewiring how wealth management works: from data aggregation and automated portfolio management to opening alternative investments like private equity and private credit to a wider investor base.
This list focuses on wealthtech platforms used by financial institutions, wealth managers, and financial advisors-not just consumer apps. The trends driving these platforms include unified operating model architectures, artificial intelligence in financial planning software, the integration of digital assets into investment portfolios, and the rise of a next generation of investors in the digital age who expect mobile-first, low-friction digital tools. For cross-border money movement that feeds these investment platforms, many globally mobile professionals pair them with a specialist app like ACE MoneyTransfer, which we introduce later as the best app for international money transfer.
Wealthtech refers to technology that modernizes investing, wealth management, and financial advice. It sits within fintech but focuses specifically on digital wealth management, portfolio management, performance reporting, and financial planning software-rather than payments or lending.
The wealthtech sector spans consumer-facing and institutional technology solutions. Consumer-facing wealthtech includes robo-advisors and digital brokers, while the institutional side powers private banks, broker dealers, and large financial institutions with sophisticated wealth management tools. The sector is experiencing significant consolidation and generational wealth transfer, which is pushing firms to replace paper-based, advisor-only models with hybrid digital wealth experiences combining self-service apps with human financial advisors. Leading players focus on segments like ultra-high-net-worth reporting and mass-market robo-advisors. In 2026, banks and wealth management firms must modernize their operating model to serve multi-jurisdictional portfolios and the next generation of clients who expect online access and seamless digital experiences.
Rather than ranking purely by size, we evaluated strategic impact on next generation digital wealth models. Key criteria included:
Scale of assets and accounts supported
Depth of digital wealth capabilities (financial planning, portfolio reporting, alternative investments)
Robust data aggregation and integration, which is crucial for high-performing wealthtech companies
Fit for regulated banking environments-platforms must comply with regulatory requirements including KYC and AML standards
Top-tier wealthtech providers offer unified architecture that presents a cohesive client view
Effective wealthtech solutions should offer seamless integration with existing banking infrastructure
Quality of APIs, system integrations, and support for a single operating model
The ranking reflects which innovative firms are shaping how wealth managers, asset managers, and individual investors experience digital wealth in 2026.
Envestnet is a cornerstone US wealthtech platform designed specifically for financial advisors, broker dealers, and large financial institutions. Envestnet manages over US$6.5 trillion in assets across 20 million client accounts, serving more than 110,000 advisors and 48 of the 50 largest wealth management firms in North America.
Its data aggregation features pull information from multiple custodians automatically, giving advisors a household-level view of client wealth-including held-away assets, bank accounts, and retirement accounts. Envestnet's ecosystem spans unified managed accounts, model marketplaces, insurance integrations, and analytics that serve as a connectivity layer across the wealth management industry. Wealthtech platforms provide a single source of truth for client data, and Envestnet exemplifies this at scale. Pricing structures vary by product and typically include AUM-based fees combined with license or subscription models. Ideal clients: mid-to-large advisory firms and institutions needing account aggregation across major custodians.
Addepar is the platform of choice for ultra-high-net-worth individuals, family offices, and private banks managing complex portfolios across asset classes, geographies, and custodians. Addepar tracks over US$7 trillion in assets for clients, serving more than 1,400 firms worldwide, with over 40% of platform assets allocated to alternative investments.
Addepar ingests data from dozens of custodians and jurisdictions-including illiquid financial assets like private equity, real estate, and venture capital-building a single data model for performance reporting and risk oversight. Its native AI tool, "Addison," delivers natural-language portfolio insights, reflecting how top wealthtech companies are increasingly integrating AI capabilities into their platforms. Addepar's pricing is based on assets under management, which can make it expensive for smaller firms but highly valuable for institutions handling multi-asset, multi-custodian complexity. It fits the tech stack as a core data and reporting layer that other wealthtech and planning systems can plug into.
FNZ is a global Platform-as-a-Service provider powering digital wealth propositions for banks, insurers, and wealth management firms. FNZ Group administers over US$1.7 trillion in assets globally, serving more than 650 financial institutions, 12,000 wealth managers, and 26 million end-investors.
FNZ combines custody, administration, trading, and client portals into a single operating model for digital wealth management. Wealthtech solutions automate onboarding, KYC, portfolio construction, and reporting-and FNZ delivers all of these within a white-label digital platform that institutions can launch quickly without building infrastructure from scratch. Its strengths in supporting multi-jurisdiction and multi-currency environments make it attractive for globally active wealth management firms and institutional investors seeking a scalable digital transformation partner.
iCapital is the leading infrastructure platform for alternative investments-private equity, private credit, hedge funds, and structured investments. By mid-2026, iCapital's platform supports over $1.2 trillion in active global assets, more than 2,600 funds, and approximately 147,000 financial professionals.
iCapital digitizes subscription, administration, and reporting for alternative investments, lowering minimums and simplifying access for advisors, private banks, and wealth management firms. Its marketplace and white-label solutions let firms embed alternatives into digital wealth and financial planning journeys. iCapital's tooling supports the next generation of investment portfolios that blend listed securities, alternative investments, and digital assets-an area where the wealth management industry is rapidly evolving.
These three vendors solve core digital platform and client experience gaps for banks building scalable digital wealth offerings. Their strength lies in regulated markets, deep integration, and the ability to unify fragmented legacy systems into one digital operating model. Wealthtech platforms automate tasks, reducing operational costs significantly, and these providers are built for exactly that purpose.
Backbase is an AI-native Banking OS that orchestrates the full client and advisor lifecycle-onboarding, servicing, and digital wealth journeys-from a single Control Plane workspace. Its Connectivity Layer offers pre-built connectors to custodians, core banking systems, and market data providers, reducing integration risk and accelerating digital banking transformation. Private banks use Backbase to digitize onboarding, cross-sell, and wealth journeys for the next generation of mobile-first clients. Wealthtech solutions enhance client engagement through marketing automation tools, and Backbase makes this practical at enterprise scale.
Bravura is an enterprise software provider for wealth management, pensions, and funds administration, with Sonata as its flagship wealth platform. Sonata supports end-to-end administration and digital engagement for advisors and clients across multiple products and jurisdictions. Its strengths include supporting complex retirement planning, wrap platforms, and long-term savings products within a single digital framework-an important capability as institutions modernize legacy back-office systems.
Avaloq serves over 170 institutions in 35 countries, with client assets of approximately USD 5.1 trillion managed through its platforms. Its SaaS and BPaaS models automate core processes while delivering personalized, omnichannel wealth experiences. Avaloq integrates portfolio management, regulatory compliance, and client engagement in a single architecture. Enterprise pricing often includes implementation fees and ongoing costs, and Avaloq's pricing reflects the depth of its front-to-back offering for private banks and wealth managers worldwide.
While primarily consumer-focused, these platforms have reshaped what next generation investors and younger investors expect from digital wealth experiences. Their innovations in automation, UX, and digital assets now influence how banks and financial advisors design their own wealth management solutions. Wealthtech platforms often use subscription models combined with asset-based tiers, and these consumer leaders set the pricing benchmarks that institutions must respond to.
Betterment pioneered the robo-advisor model with automated investing, goal-based financial planning, tax loss harvesting, and portfolios of low cost ETFs. Betterment has over 1 million customers and more than US$70 billion in assets under management. It runs a dual strategy: direct-to-consumer investing and Betterment for Advisors, supporting independent RIAs. Betterment charges a percentage of AUM for managed accounts, demonstrating the power of automation in delivering affordable financial planning at scale. Leading wealthtech firms enable personalization at scale using goal-based planning and AI, and Betterment is a clear example.
Wealthfront is a direct-to-consumer digital wealth platform known for automated investing, direct indexing, and high yield cash accounts. It targets self-directed, digitally native investors who prefer algorithmic financial planning and minimal human interaction. Automated investment platforms streamline portfolio management tasks, and Wealthfront's product design-combining cash, investment services, and planning in a single app-continues to influence how banks think about unified client relationships. Following its continued independence post-UBS deal collapse, Wealthfront has expanded its digital platform with new banking and management tools.
Robinhood is the commission free trading app that democratized online access to stocks, ETFs, options, and cryptocurrencies. Robinhood has a significant user base of younger investors who use it as an on-ramp to investing before engaging traditional financial advisors. By 2026, expansions into retirement accounts, cash management, and more structured portfolio offerings have matured its positioning. Robinhood's gamified UX and focus on digital assets have pushed traditional institutions to upgrade their own investing and education experiences, raising the bar for cutting edge technology in client portals across the wealth management industry.
AI is becoming a major differentiator in wealthtech for automating portfolio management, and Deloitte projects that agentic AI could free 25% to 50% of adviser time currently spent on operational tasks by 2032, a shift that could reshape how financial expertise is delivered. Here's how to map wealthtech platforms to your needs:
Match core processing and client experience needs to platforms like FNZ, Avaloq, or Backbase
Use Addepar or Envestnet for data aggregation and unified client data across custodians and asset classes
Embed alternative investments via iCapital for private equity, private credit, and hedge funds
Study consumer wealthtech (Betterment, Wealthfront, Robinhood) to benchmark what your clients expect from transparent financial solutions
Assess vendors on scalability, AI-readiness, and integration depth-not demos alone
Support both existing clients and the next generation of digital-first investors who expect seamless digital wealth experiences
Wealthtech platforms automate investing and client service tasks, and the right combination of platforms delivers a single operating model with fewer fragmented tools and more unified workflows. Many clients also fund their investment portfolios from overseas income or remittances-which is where cross-border money movement becomes essential.
As digital finance continues to evolve, managing money across borders has become an important part of modern financial activity. ACE Money Transfer provides a digital channel for international remittances, allowing customers to send money through supported corridors using its online platform and mobile app.
Customers can set up transfers digitally, review applicable fees and exchange rates, and select the available delivery method for their chosen destination. Depending on the corridor, delivery options can include bank deposits, cash pickup, mobile wallets, and other country-specific methods.
Rates and fees may vary, and exchange rates fluctuate, so the rate you receive may differ from any quoted rate. Always check the live rate at ACE Money Transfer before sending.
While WealthTech platforms focus primarily on digital wealth management and investment-related services, ACE serves a different part of the financial ecosystem by supporting international money transfers and helping customers manage cross-border financial commitments through digital channels.
ACE MoneyTransfer is the best app for international money transfer, complementing wealthtech platforms by moving funds quickly and cost-effectively across borders. Globally mobile professionals and expatriates use AceMoneyTransfer to send money from their country of work to their home bank or brokerage, where it can then be invested through the top 10 wealthtech companies profiled above.
Key advantages include competitive FX rates, low cost transfer fees, fast delivery times, and support for multiple corridors commonly used by next generation investors-including Asia-US, Europe-US, and Africa-Middle East routes. The app delivers an intuitive mobile UX, real-time tracking, compliance with major regulations, and secure handling of digital transactions that ultimately feed into digital wealth and financial planning goals.
If you're building a modern investor's digital stack, ACE MoneyTransfer sits right alongside your wealthtech platforms-connecting global income to local investment opportunities, every day.
Disclaimer: This article is intended for general informational and educational purposes only and should not be construed as legal, regulatory, tax, business, or financial advice. While reasonable efforts have been made to ensure that all facts, figures, and data are accurate and valid as of the date of publication, no warranty or guarantee is given as to the ongoing completeness, accuracy, or currency of the information.
The content is based on information available at the time of publication. Regulations, government policies, market conditions, and service offerings may change over time and vary across jurisdictions and providers. As a result, some information may no longer be current or applicable. Readers should independently verify all information and consult qualified professional advisors before making any financial, legal, or business decisions.