ACE Money Transfer
ACE Money Transfer
17 Sep 2026
Buy now pay later has evolved from a checkout gimmick into a core payment method for millions of shoppers. In 2026, BNPL services let you split purchases into four interest free payments, spread costs over monthly payment schedules, or choose longer installment payment plans - all without applying for a traditional credit card. Most BNPL apps are embedded directly in online and in store checkout flows, showing you exact payment schedules and amounts before you accept, which makes making purchases feel almost frictionless.
Many BNPL providers use alternative approval processes, which may involve soft credit checks or other risk assessments depending on the provider. That lighter approval process is a big reason Gen Z and Millennials have embraced the BNPL space. Still, these services are not free money. Missed payments can trigger late fees and, depending on the provider, negative credit reporting that affects your credit score.
The global BNPL market was valued at approximately US$492.8 billion in 2024 and is projected to reach US$911.8 billion by 2030, according to Research and Markets' Buy Now Pay Later Global Business Report 2025. The BNPL market is clearly still accelerating. This guide highlights the top 10 buy now pay later platforms, then compares them on fees, flexibility, and how they treat your credit profile - so you can pick the right BNPL app before your next purchase.
Here are the top BNPL apps for 2026. Major BNPL providers include Klarna, Afterpay, Affirm, PayPal Pay Later, Sezzle, and Zip, alongside strong regional and niche players.
Affirm - best for long repayment terms
Klarna - best for multiple repayment options
Afterpay - best for simple pay in 4
PayPal Pay Later - best for existing PayPal users
Zip - best for global coverage
Sezzle - best for payment flexibility
Perpay - best for building credit scores
Cash App Afterpay - best for in-app shopping
Zilch - best for virtual card payments
Tamara - best for Middle East shoppers
All ten are established BNPL companies, but availability, interest free plans, and fees vary by country. Some operate only in specific regions, while others offer flexible payment options across multiple markets. Always confirm that a provider is available where you shop online or in store before signing up.
Most BNPL apps work similarly at checkout, but the details differ in ways that matter for your wallet and credit. The use of BNPL can help with budgeting by breaking large costs into predictable chunks, and BNPL platforms commonly offer apps for tracking due dates and balances. Before you commit, weigh several factors:
Purchase amount and credit limit - some apps cap first-time users at a few hundred dollars; others support larger purchases up to $10,000+.
Pay in 4 vs. pay monthly - short-term interest free payments suit small buys; longer plans work for big-ticket items but may include interest charges.
Late fees and hidden fees - some providers charge fees for missed or failed payments; others, like Affirm, charge none.
Credit reporting - does the app report on time payments to bureaus (helpful for building credit) or only flag missed payments?
Country availability - shoppers in the Middle East, Southeast Asia, or Africa need region-specific BNPL providers.
App experience - look for clear due-date reminders, automatic payments, and spending insights.
Quick profiles to guide your choice:
Frequent small purchases ? Afterpay or Zilch
Occasional big-ticket items ? Affirm or PayPal Pay Later
Limited or poor credit ? Perpay or Sezzle
International or Middle East shopper ? Tamara or Zip
If you regularly send money abroad - for example, to family - keep BNPL and remittances separate. Use a specialised money transfer app like ACE Money Transfer for international transfers rather than trying to repurpose a BNPL app for something it was never designed to do.
Affirm is a US-based financial technology company founded in 2012 in San Francisco. It built its reputation on transparent pricing and zero hidden fees. Affirm charges no fees for its BNPL services - no late fees, no prepayment penalties - making it an attractive option for budget-conscious shoppers making purchases across thousands of ecommerce and in store retailers.
Pay in 4 - four interest free payments on eligible purchases via a soft credit check.
Longer financing - Affirm provides customizable payment plans from three months to several years, with APR ranging from 0% to roughly 36% based on your credit profile, the merchant, and the loan amount.
Approval - uses a soft credit inquiry (no hard credit check), so applying doesn't hurt your credit score. However, missed payments on longer instalment loans may be reported to bureaus.
Pros: Ideal for larger purchases with extended timelines; no late fees ever; clear disclosure of total cost before you accept.
Cons: Longer-term plans carry interest rate costs; approval for the best rates depends on strong credit; not the cheapest for short-term, fully interest free BNPL payment needs.
In 2026, Affirmupgraded its underwriting model to incorporate real-time signals like bank balances and cash flow trends, helping it more accurately assess affordability for BNPL users.
Klarna is a Sweden-founded BNPL company serving approximately 118 million active consumers worldwide. Its BNPL app is one of the most popular digital payments tools in Europe and North America, packed with shopping features, exclusive deals, and a broad merchant network.
Pay in 4 - four interest free payments, bi-weekly, with a soft credit check.
Pay in 30 days - buy now, pay the full amount within 30 days, interest free.
Financing - Klarna offers financing for up to 36 months with APR that varies by country and offer (roughly 0%–35.99%).
Klarna provides multiple payment options including pay in four and pay in 30 days, giving users flexibility most bnpl providers cannot match.
Pros: Extremely flexible pay later options; strong BNPL app with price-drop alerts, wishlists, and in-app shopping; massive global network of partner stores.
Cons: Klarna charges a late fee up to $7 for missed payments; longer financing plans have complex fee structures; the convenience can encourage overspending if you aren't disciplined.
At checkout, Klarna shows available payment plan options with exact amounts and due dates, so you know precisely what you owe before confirming.
Afterpay was founded in Australia and is now part of Block (formerly Square). It popularised the straightforward "pay in 4" model and operates in the US, Canada, UK (as Clearpay), Australia, and New Zealand. In the US, it is also accessible as Cash App Afterpay, embedded directly inside Cash App.
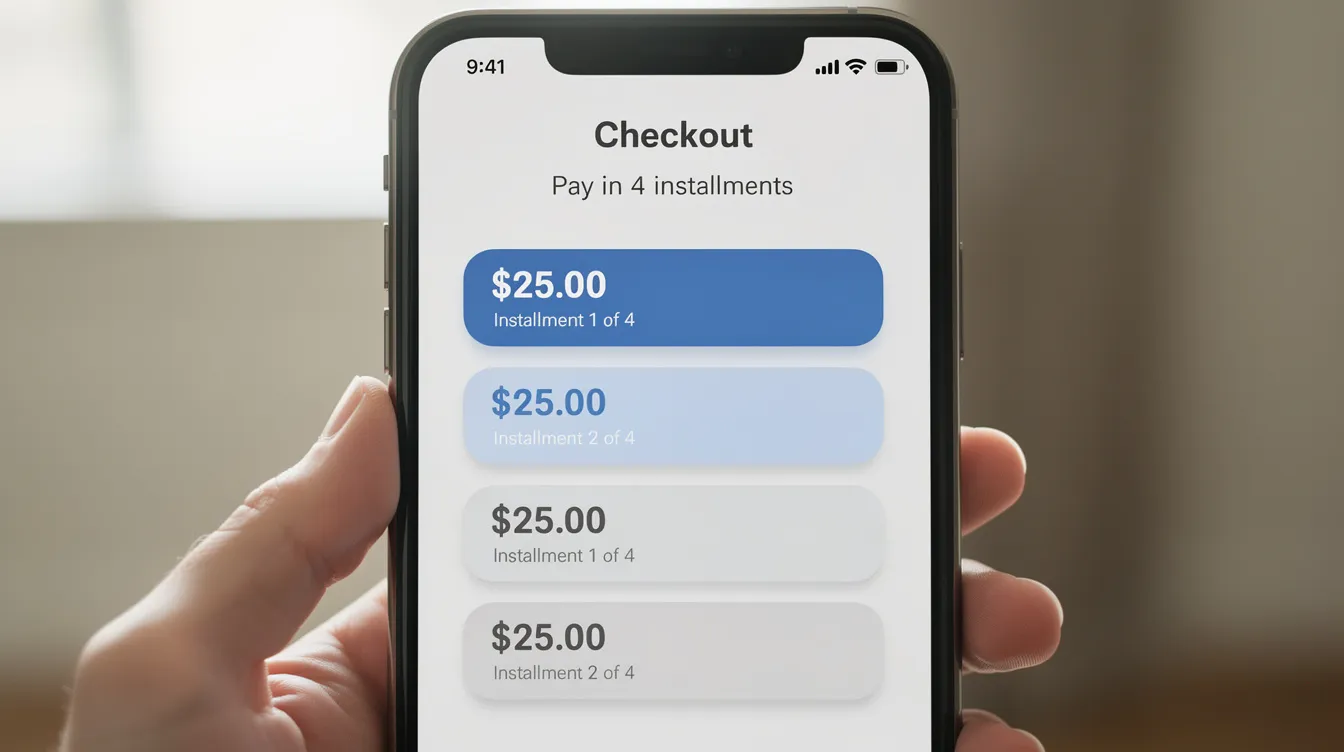
Core product - Afterpay allows payments in four installments due every two weeks, interest free. That means you pay over six weeks with zero interest if you stay on schedule.
Afterpay remains one of the most recognized pay-in-four providers in major markets.
Approval - soft, real-time risk assessment based on account history, past repayment behaviour, and transaction size. No hard credit inquiry.
Pros: Dead simple; widely accepted at fashion, lifestyle, and general retail merchants; integrated inside Cash App for easy in-app shopping and direct payments.
Cons: Afterpay charges a late fee up to $8 for missed payments; initial spending limits can feel low; no long-term financing option for bigger purchase amounts.
When Afterpay makes sense: You want a quick, interest free way to split a purchase under a few hundred dollars. When it doesn't: You need to finance a $2,000 appliance over 12 months.
PayPal leads the BNPL market with 68.1% user share, largely because millions of merchants already accept PayPal. Adding its pay later option at checkout is seamless for anyone with an existing PayPal account.
Pay in 4 - PayPal offers four interest free payments over six weeks for eligible purchases between roughlyUS$30 and $1,500. No interest, no fees if paid on time.
Pay Monthly - longer instalment loans from 3 to 24 months for purchases up to approximately US$10,000, with APR between roughly 9.99% and 35.99% depending on credit, state, and merchant.
Approval - Pay in 4 uses a soft credit check with no impact on your credit score. Pay Monthly involves a more detailed credit assessment and may include a hard credit inquiry.
Pros: Unmatched convenience for PayPal users; strong buyer protection ecosystem; manage BNPL plans and standard PayPal digital payments in one app.
Cons: Interest on Pay Monthly plans can be high; not all PayPal regions offer identical BNPL features; payment history on Pay in 4 generally isn't reported to credit bureaus, so it won't help with building credit directly.
Zip is an Australian-origin BNPL provider operating across Australia, New Zealand, the US, and other markets. It stands out for its virtual card model and flexible scheduling.
Pay in 4 or pay in 8 - bi-weekly interest free instalments, though Zip may charge an origination fee between $0 to $124 depending on the plan and state.
Virtual card - many providers allow users to generate virtual cards for shopping at various retailers, and Zip's version lets you shop online or in store wherever Mastercard or Visa is accepted.
Alignment with pay cycles - Zip lets you schedule payments around your weekly, fortnightly, or monthly payment dates.
Pros: Broad acceptance thanks to virtual cards; flexibility to align split payments with your paycheck; available in multiple countries across its global network.
Cons: Fees can add up compared with pure interest free plans; service availability and features still vary by country; the origination fee catches some users off guard.
Sezzle is a North American BNPL app that offers buy now, pay later services to consumers in the United States. Its standout feature is the ability to reschedule instalments - Sezzle allows users to reschedule payments without penalty for the first time, giving you breathing room if a due date lands at a bad time.
Pay in 4 - four interest free payments, bi-weekly.
Longer plans - 3 to 48 months via partner lenders, with interest rate terms set by the lending partner.
Rescheduling - first reschedule is free; additional reschedules carry modest fees.
Credit building - some Sezzle plans optionally report positive payment history to bureaus.
Pros: Strong budgeting tools, genuine payment flexibility, and some credit-building potential for BNPL customers who opt in.
Cons: Sezzle charges a late fee up to $16.95 for missed payments - late payments can incur fees up to $16.95, making it one of the more expensive penalties among top bnpl apps. Geographic availability is mainly US and Canada, and stacking multiple concurrent Sezzle orders increases the risk of overextension.
Perpay is a US-based BNPL provider that takes a different approach: repayments are deducted directly from your paycheck, reducing the chance of missed payments almost entirely.
Target audience - consumers with fair or limited credit scores looking for a pathway to building credit through responsible instalment payment behaviour.
Product structure - you shop through Perpay's own marketplace. Instalments are automatically deducted each pay period, often interest free, though product prices in the marketplace may be slightly higher, effectively embedding financing costs.
Credit reporting - Perpay reports on time payments to major credit bureaus, which may help users build credit history when payments are reported and managed responsibly.
Pros: Disciplined, automatic payments mean fewer slip-ups; genuinely useful for building a positive credit profile; predictable deductions aligned with payroll.
Cons: Limited to Perpay's marketplace rather than all retailers; requires steady employment; not available outside the US; the embedded cost structure means you may pay more than the retail price elsewhere.
Zilch is a UK-based BNPL app that has grown to over5 million registered customers. It partners with both Mastercard and Visa, enabling users to pay anywhere those cards are accepted using a virtual or physical card.
Pay now with rewards - pay in full and earn cashback-style rewards.
Pay over six weeks - split into interest free instalments if paid on schedule.
Pay over 3, 6, or 12 months - available for eligible users, with fees (e.g., around 6% of purchase price for 3-month plans, capped at roughly £40).
Tap & pay-over-time - Zilchlaunched a tap-and-pay feature in 2026 compatible with Apple Pay, Google Pay, and Samsung Pay.
Pros: Broad merchant acceptance beyond a fixed store list; clear BNPL app experience with spending insights powered by artificial intelligence; works for everyday in store and online spending.
Cons: Currently focused on UK and European users; subject to newFCA regulation of deferred payment credit effective July 2026; frequent small BNPL use for everyday items can encourage overspending if unchecked.
Tamara is a leading buy now pay later provider in Saudi Arabia and the wider Middle East, founded in 2020 and expanding rapidly across GCC markets including the UAE. For shoppers in the region, it is the standout BNPL app.
Core product - pay in 3 equal instalments over 60 days, interest free if paid on time, denominated in SAR and AED.
Regulatory milestone - Tamara was the first BNPL company to receive a sandbox licence from the Saudi Central Bank (SAMA), signalling strong local compliance and trust from financial institutions.
Arabic-language support and partnerships with major regional ecommerce and retail brands.
Pros: Purpose-built for Middle East shoppers; interest free plans in local currencies; strong compliance posture; growing merchant coverage.
Cons: Mainly available in GCC markets; fewer long-term financing options than global later apps like Affirm or Klarna.
Other Middle East BNPL providers like Tabby and Cashew compete in the same space, but Tamara remains the most widely cited example for the region's later market.
Beyond the core top 10, several notable later apps serve specific niches or regions:
Cash App Afterpay (US) - integrated inside Cash App, great for users already sending and receiving money there; splits purchases into four installments with the same Afterpay terms.
BillEase (Philippines) - a local BNPL app with a retail credit focus, offering financial products tailored to Filipino consumers.
Lipa Later (Kenya and East Africa) - an example of BNPL providers driving financial inclusion in Africa, serving populations with limited access to traditional credit.
Klarna, Zip, or Atome - for Southeast Asia and emerging markets, each adapting their model to local regulations and consumer behaviour.
Availability and regulation vary by country, so always confirm which BNPL apps and later services actually operate in your market before signing up.
BNPL, credit cards, and money transfer apps serve fundamentally different purposes. Confusing them leads to poor financial decisions.
Feature | BNPL Apps | Credit Cards | Money Transfer Apps |
| Primary use | Split retail purchases | Revolving credit for purchases | Send money internationally |
| Credit check | Usually soft (no hard credit check) | Hard credit inquiry | Typically none |
| Interest | Often interest free short-term | Interest on carried balances | N/A - fee-based |
| Credit score impact | Limited unless payments missed | Directly affects credit | No impact |
ACE Money Transfer is a dedicated international remittance service designed for sending money across borders. It serves a different purpose from BNPL platforms, which are designed for installment payments. It is designed for sending money abroad - for example, to family in Asia, Africa, or the Middle East - not for financing retail purchases. Avoid funding BNPL repayments with borrowed remittance money; which can increase the risk of taking on repayments you may not be able to manage.
Treat spending tools (BNPL and credit cards) and cross-border transfer services (ACE Money Transfer) as distinct components in a healthy financial toolkit. Cash advance apps and BNPL apps solve different problems than a dedicated remittance platform with a global network built for direct payments across borders.
Overspending is common with BNPL services. The frictionless checkout experience makes it easy to buy now pay later without pausing to ask whether you have enough money to actually repay. BNPL users often have higher overall debt levels than non-users, and overextension can occur when consumers stack multiple BNPL plans at once. Late payments may lead to fees and negative credit reporting depending on the provider. Several BNPL products do not routinely report payment history to major credit bureaus, meaning you get punished for mistakes but may not be rewarded for good behaviour.
Specific risks to watch:
Difficulty tracking multiple due dates across different BNPL apps - each app has its own schedule, and juggling them without automatic payments is stressful.
Refunds can be difficult to obtain after BNPL purchases, often slower and more complex than direct card chargebacks.
BNPL fraud risks - BNPL services face fraud risks including account takeover and identity theft.
Practical safety tips: limit the number of active BNPL plans at any one time; avoid using BNPL for nonessential spending you couldn't otherwise afford; turn on reminders and automatic payments from a stable debit card or bank account; regularly check statements and your credit report.
For larger, long-term needs - education, medical expenses, debt consolidation - a personal loan or 0% intro APR credit card from established financial institutions may be more appropriate than stretching BNPL plans beyond their intended scope.
Do BNPL apps affect my credit score? Many providers use soft credit checks that do not harm your credit score during approval. However, late payments on some platforms can trigger negative reporting. A few services, like Perpay, proactively report on time payments, which can help with building credit over time. The impact depends on the specific provider and your payment history.
Are buy now pay later services really interest free? Short-term plans (pay in 4) are typically interest free if you make on time payments. Longer financing - like Klarna's 36-month option or PayPal's Pay Monthly - carries interest charges. Watch for high fees, origination fees, and late fees that can make "interest free" more expensive than it appears.
Can I use multiple BNPL apps at the same time? Yes, but it is risky. Stacking plans across different bnpl apps makes it easy to lose track of due dates, overspend, and fall behind on payments. Most bnpl apps do not share data with each other, so no single provider sees your full picture.
Is BNPL available in the Middle East and emerging markets? Yes. Later companies like Tamara (Saudi Arabia, UAE), Tabby, and Cashew serves the Middle East. In Southeast Asia, Atome and Grab PayLater are popular. In East Africa, Lipa Later is expanding. Regulation and features differ by country.
Is it safe to link my bank account or card to a BNPL app? Reputable BNPL providers use encryption and fraud detection similar to major banks. Use strong passwords, enable two-factor authentication, and avoid linking accounts on public Wi-Fi. Review each provider's security practices before sharing financial products or account details.
Answers may vary by provider and country - always review the specific BNPL provider's terms before agreeing to a payment plan. Use buy now pay later responsibly alongside traditional banking tools, and rely on a dedicated money transfer app such as ACE Money Transfer when you need to send funds across borders.
Disclaimer: This article is intended for general informational and educational purposes only and should not be construed as legal, regulatory, tax, business, or financial advice. While reasonable efforts have been made to ensure that all facts, figures, and data are accurate and valid as of the date of publication, no warranty or guarantee is given as to the ongoing completeness, accuracy, or currency of the information.
The content is based on information available at the time of publication. Regulations, government policies, market conditions, and service offerings may change over time and vary across jurisdictions and providers. As a result, some information may no longer be current or applicable. Readers should independently verify all information and consult qualified professional advisors before making any financial, legal, or business decisions.