ACE Money Transfer
ACE Money Transfer
17 Sep 2026
Managing money digitally has moved from a novelty to a necessity in Pakistan. Whether you need to pay bills, send money to family members, or shop online, a mobile wallet now handles what used to require a trip to a bank branch or agent counter. This guide breaks down the top 10 mobile wallets in Pakistan, compares their fees and features.
Mobile wallets and branchless banking wallets dominate day-to-day payments, bill payments, and mobile top ups across Pakistan. The top mobile wallets in Pakistan are JazzCash, Easypaisa, NayaPay, and SadaPay, but several other strong options round out a competitive field. Easypaisa and JazzCash dominate for cash access and everyday domestic payments.
Here are the current top 10:
JazzCash – Largest branchless banking wallet with the biggest agent network
Easypaisa – Pioneer of mobile money with micro-loans and digital bank status
NayaPay – Visa-powered EMI wallet for students and freelancers
SadaPay – Minimal-fee Mastercard wallet for digital natives
Zindigi by JS Bank – Payments plus stock market and mutual fund investing
Alfa by Bank Alfalah – Full hybrid bank account and digital wallet
UPaisa – Best for Ufone subscribers and simple branchless banking
Finja Wallet – SME-focused EMI with payroll and credit tools
Konnect by HBL – Ideal for salary disbursements and government payments
Keenu Wallet – POS-driven wallet with merchant cashback offers
ACE Money Transfer – ACE Money Transfer provides international money transfer services that can complement existing mobile wallet and banking arrangements.
Rankings reflect user base, merchant acceptance, transaction fees, Raast compatibility, and support for e commerce.
Pakistan's digital financial ecosystem features telco-backed branchless banking apps and fintech neo-wallets that have collectively reshaped how millions handle money. Growth accelerated after COVID-19 pushed consumers away from carrying cash, and the launch of Raast as the country's instant payment rails cemented the shift. Over 175 million people adopted digital wallets in Pakistan by 2020, and adoption has only climbed since.
A mobile wallet is simply an app linked to your CNIC (and optionally a bank account) that lets you pay bills, send money transfers, make QR payments at shops, and buy mobile top ups - all with just a few taps. By 2025–2026, tens of millions of Pakistani adults rely on these wallets daily, driven by rising e commerce, ride-hailing, food delivery, and utility bill payments moving online.
Raast is becoming the foundation of instant digital payments in Pakistan, enabling instant transfers between participating banks and wallets. Digital banking expansion is expected as traditional banks invest in technology, while QR payments are likely to become a standard payment method across the country. This guide compares the best mobile wallets, their transaction fees, strengths, and ideal users - and explains how overseas Pakistanis can fund these wallets efficiently via ACE Money Transfer.
Not every wallet is ranked purely by size. A smaller EMI with zero fees and a Visa debit card may be a better fit than a giant branchless banking wallet if you never visit an agent shop. Here is what we evaluated:
User base and adoption – Monthly active users and growth trajectory
Merchant and biller coverage – How many shops, utility companies, and online stores accept the wallet
Transaction fees and hidden charges – Cash-in, cash-out, transfer, and international costs
Mobile app experience – Design, speed, reliability
Security and SBP licensing – Whether the wallet provider operates as an EMI or microfinance bank under State Bank of Pakistan rules
Raast and payment gateways compatibility – Support for instant payment rails and e commerce checkouts
Segment suitability – Fit for students, freelancers, SMEs, rural users, or urban users
Information is based on public data and typical 2025–2026 fee structures. Always check each provider's latest schedule of charges before committing.
JazzCash is Pakistan's biggest mobile wallet and branchless banking service, owned by Mobilink Microfinance Bank. JazzCash features the largest active user base and agent network in Pakistan.
Key features: Wallet-to-wallet transfers, transfers to any bank account, Raast, utility and government bill payments, mobile top ups for all networks, QR payments, debit card, insurance, and savings products.
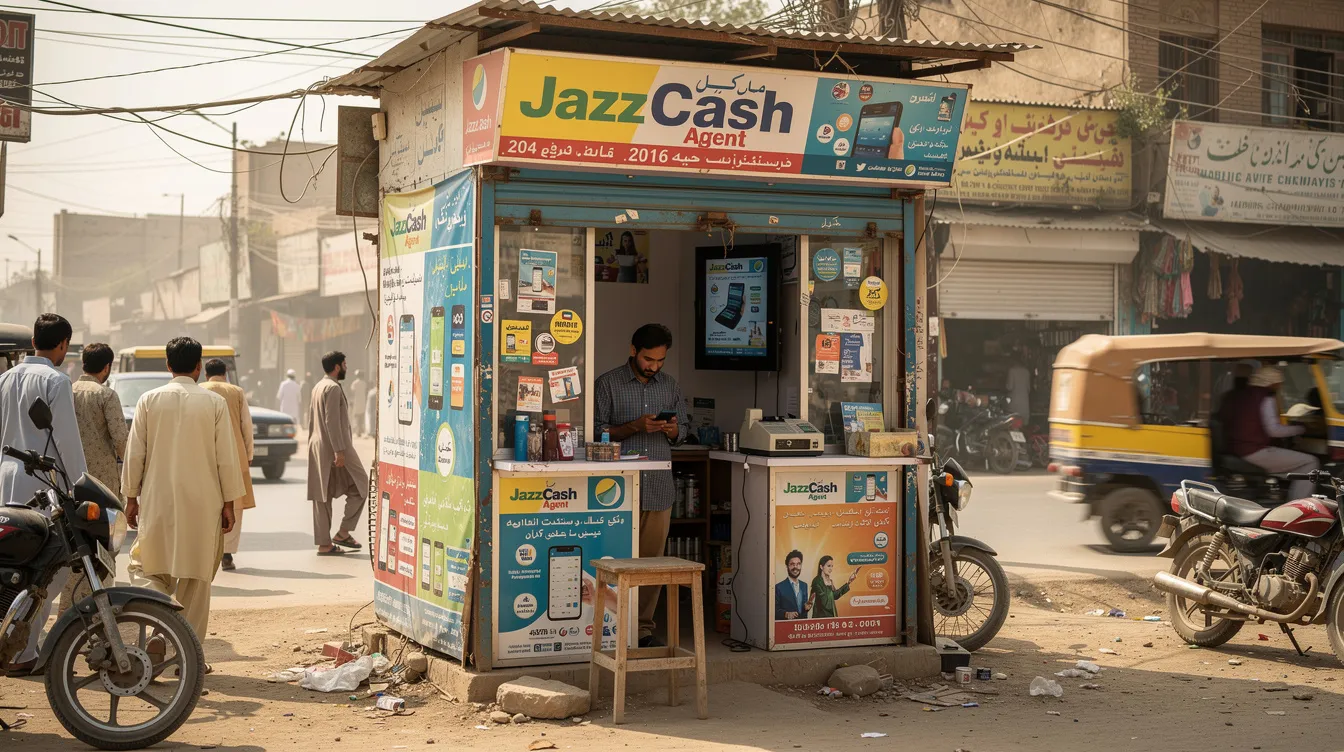
Physical reach: JazzCash has over 100,000 local retail agents in Pakistan (the figure tops 300,000 when including all retail partners), making it ideal for cash heavy users who frequently cash in or withdraw cash. Both JazzCash and Easypaisa support cash deposits and withdrawals via a large agent network.
Transaction fees: Wallet-to-wallet is mostly free. Tiered charges apply on OTC/CNIC transfers, agent cash out, and some bill payments. Watch small repeated fees - they add up.
Ideal for: Small businesses taking QR payments, salary disbursements, routine utility bill payments, and people in rural areas needing cash out accessibility.
E commerce: JazzCash appears alongside cards and bank transfers at most major payment gateways and online checkouts.
JazzCash processes over 80% of total Raast payment value, making it the backbone of Pakistan's digital payment infrastructure.
Easypaisa was launched in 2009 by Telenor Microfinance Bank as Pakistan's first large-scale branchless banking wallet. It has over 25 million users and, in January 2025, received Pakistan's first digital bank license from the State Bank.
Features: Money transfers, bill payments, mobile top ups, savings pockets, Easycash micro-loans, insurance, and QR merchant payments. Easypaisa is known for its strong local utility and bill payment features.
Agent network: Easypaisa has a cash agent network that serves millions in rural areas, with a strong agent and shop footprint nationwide for deposits, withdrawals, and remittance payouts.
Fees: App-to-app and Raast transfers are often free or low cost. Agent transactions, cash withdrawals, loan processing, and SMS alerts can add up in transaction fees. No significant hidden fees on standard digital transfers.
User profile: Great for people who need both digital payments and access to small loans, or who live where traditional bank branches are sparse - a cornerstone of financial inclusion.
Integration: Easypaisa is a common checkout option across e commerce platforms and ride-hailing apps.
NayaPay is a State Bank of Pakistan-licensed EMI that provides a CNIC-linked wallet, free virtual and physical Visa debit cards, and an app-first banking experience. NayaPay is designed for card-based and online spending with modern fintech features.
Features: Instant Raast transfers to any bank account, bill payments, mobile top ups, in-app payment requests, bill splitting, and shared expense tools.
Cards and e commerce: NayaPay provides a free Visa debit card for international transactions and international payments on Pakistani and global merchants, streaming platforms, and online stores - strong for international subscriptions. NayaPay supports free Visa debit cards for international transactions.
Fees: Generally zero monthly charges, no local wallet or bank transfer fees. Standard ATM withdrawals and international card usage costs apply. NayaPay allows seamless money transfers for digital professionals.
Best for: University students, roommates managing shared bills, and freelancers needing a low-fee card for global digital financial services. NayaPay is ideal for freelancers with Payoneer support.
Limitation: NayaPay and SadaPay focus on digital-first experiences without an extensive agent network, so cash in typically happens via bank account transfers or salary deposits.
SadaPay is an EMI focused on app-only banking with a modern interface. It offers a Mastercard debit card and was acquired by Papara (Turkey) in 2024, boosting its tech stack. SadaPay is designed for digital-native users and freelancers.
Features: Instant transfers to banks and wallets, bill payments, mobile top ups, Raast support, in-app card controls, and virtual cards for online shopping.
Fees: SadaPay charges no fees for local wallet transfers. No monthly charges, transparent pricing. SadaPay offers zero foreign transaction fees for international purchases - a standout for anyone who needs to shop online internationally or pay for global subscriptions. SadaPay offers a Mastercard with zero foreign transaction fees.
Strengths: Very clean UI, real-time notifications, spending analytics, and transaction history. SadaPay and NayaPay offer superior digital experiences and international card usability compared to branchless wallets.
Limitations: No branchless agent network and no USSD fallback. Cash deposits must come via bank transfers or salaries.
Best for: Paying for global digital services, managing student budgets, and pairing with ACE Money Transfer remittances that arrive first in a bank account then move into SadaPay.
Zindigi is JS Bank's app-first digital wallet aimed at Gen-Z and younger users, combining payments and investments in a single platform.
Payment features: Wallet linked to a JS Bank account, QR payments, Raast transfers, bill payments, and mobile top ups.
Investment features: Direct access to Pakistan Stock Exchange (PSX) trading, mutual funds, and simple savings instruments from inside the app.
Target users: Salary earners and students who want one app for day-to-day payments plus beginner-friendly investing.
Fees: Local digital transfers typically low cost. Brokerage and fund transactions carry standard financial market charges - check in-app for current rates.
Edge: Zindigi benefits from JS Bank's regulated infrastructure, giving users traditional bank security with a modern e wallet experience.
Alfa is Bank Alfalah's flagship digital banking and mobile wallet app, tying directly into full bank accounts, cards, and lending products. It functions as both the best digital wallet for Bank Alfalah customers and a standalone digital channel.
Core capabilities: Manage Bank Alfalah accounts and cards, open digital accounts, pay bills, send money via Raast and IBFT, make QR and POS payments, and top up mobile numbers.
Hybrid role: Alfa works as both an e wallet and a control centre for Bank Alfalah credit cards, loans, and savings accounts.
Existing customers: Instant visibility of balances, card controls, instalment plans, and a seamless card-to-wallet experience.
Fees: Most in-app transfers and bill payments are competitively priced. IBFT is free up to PKR 25,000 per month; beyond that, 0.1% or Rs. 200 (whichever is lower) per transaction.
Ideal for: Users already banking with Bank Alfalah, online shoppers who prefer card-backed wallets, and people wanting a single app for both digital wallet and full-service banking.
UPaisa is Ufone's branchless banking wallet, tightly integrated with Ufone prepaid and postpaid connections.
Services: Send money to CNIC, bank accounts, and other wallets. Pay utility bills and Ufone bills, buy mobile top ups, use QR payments, and access limited savings products.
Account opening: Sign up via Ufone number and CNIC - simple and accessible for users who already trust their mobile operator.
Pricing: Competitive mobile top up offers and standard agent cash-in/out charges similar to JazzCash and Easypaisa models.
Strengths: Particularly convenient for Ufone customers and those in locations where UPaisa agents are common.
Positioning: Less dominant than JazzCash or Easypaisa but a solid secondary wallet for mobile top ups and basic bill payments.
Finja is an EMI licensed by the State Bank of Pakistan that focuses on small businesses, digital payroll, and credit alongside consumer wallets.
Wallet features: P2P transfers, bill payments, mobile top ups, QR and online merchant payments, and integration with business tools. Finja also supports digital invoicing for merchants.
SME benefits: Salary disbursement to staff wallets, invoice and supplier payments, access to working-capital loans based on transaction history, and payment links for collecting dues.
E commerce fit: Potential integration with payment gateways and POS systems for small merchants.
Fees: Low-fee digital transfers. Business services like payroll processing or merchant collections are priced on a transparent schedule with no hidden costs.
Best for: Shop owners, small manufacturers, and services businesses wanting to move from physical cash to structured digital payments.
Konnect is HBL's branchless banking wallet, widely used for salary disbursement, government schemes, and cash-light payments.
Features: Receiving salaries or stipends, Raast transfers, bill payments, mobile top ups, QR merchant payments, and card options.
Financial inclusion: Often used in aid and government disbursement programmes where people receive funds into Konnect instead of cash - critical for reaching unbanked populations.
Agent access: HBL's large footprint and agent network make withdrawals and deposits relatively easy across cities and smaller towns.
Fees: Similar to other branchless banking wallets - low-cost wallet transfers but charges on cash-outs and OTC transactions.
Ideal users: Employees whose companies or NGOs pay via Konnect, and unbanked individuals looking for a first simple digital wallet.
Keenu is a payments company known for POS machines that also offers a consumer mobile wallet for QR and in-store payments. It is one of the newer EMIs granted commercial operations by SBP.
Features: Wallet top ups from bank accounts, QR payments at Keenu-enabled merchants, bill payments, and mobile top ups.
Merchant angle: Keenu wallet ties into Keenu POS and QR infrastructure, giving users discounts and cashback offers at partner stores and restaurants.
Typical user: Urban shoppers in malls and food outlets where Keenu terminals are common, and people who enjoy promo-driven in-store QR payments.
Costs: Digital payments are often free for the consumer, with merchants paying MDR via Keenu's acquiring side. Check for seasonal promo campaigns.
Role: A good "extra wallet" alongside a primary account like JazzCash, Easypaisa, NayaPay, or SadaPay.
ACE Money Transfer is not a domestic mobile wallet. However, it is the best money transfer app for overseas Pakistanis sending international remittances into bank accounts and major wallets back home. If you live in Europe, the UK, North America, or other regions, ACE is how you fund your family's wallets efficiently.
Payout options: Direct credit to Pakistani bank accounts (which recipients then move into any selected wallet), cash pick-up at partner locations, and in some cases direct wallet deposits into JazzCash, Easypaisa, NayaPay, and SadaPay.
Advantages: Competitive exchange rates with transparent fees and forex margins, low or zero transfer fees on promotional corridors, credit times often under 10 minutes for wallet or cash pick-up, and 24/7 app access. No hidden fees on clearly marked corridors.
Common use case: Expatriates using ACE Money Transfer for regular family support, bill payments, and education fees. Recipients then use JazzCash, Easypaisa, NayaPay, SadaPay, or Alfa to manage money and handle spending locally.
Safety: Regulated in sending countries and working only with licensed banks and payment partners in Pakistan. Always check the latest list of supported banks and wallets in the ACE app.
ACE vs traditional agents: App-based transfers like ACE offer lower fees, faster processing, better conversion rates, and the convenience of sending from your phone - compared to visiting a physical remittance agent and dealing with foreign currency markups.
Rates and fees may vary, and exchange rates fluctuate, so the rate you receive may differ from any quoted rate. Always check the live rate at ACE Money Transfer before sending.
No single best digital wallet exists for everyone. Compare these features against your lifestyle before choosing where to manage money:
Bill payments: JazzCash, Easypaisa, and Alfa cover the widest range of utility companies, internet providers, education fees, and government charges.
Mobile top ups: All wallets support all mobile operators. Look for cashback offers and scheduled auto-top-ups (NayaPay and SadaPay offer clean interfaces for this).
Bank account connectivity: Raast makes free bank transfers possible across most wallets. Check deposit and withdrawal speeds.
Transaction fees: Branchless banking wallets tend to charge on cash-in/out and OTC. EMIs like SadaPay and NayaPay minimise digital-only fees with lower fees across the board for online purchases.
Cards and international payments: NayaPay offers Visa debit cards; SadaPay offers Mastercard. Both work on global websites. Note that Apple Pay is not natively supported in Pakistan yet, though Google Wallet launched NFC tap-to-pay support in March 2025.
Business compatibility: Acceptance via major payment gateways, QR codes in shops, and options for merchants and freelancers. Fintech companies like Finja offer dedicated merchant acceptance tools.
All major wallets in this list operate under State Bank of Pakistan regulation, either as microfinance banks (branchless banking wallets) or as licensed EMIs. Major wallets operate under State Bank of Pakistan oversight. All four top wallets - JazzCash, Easypaisa, NayaPay, and SadaPay - are regulated by the State Bank of Pakistan for security standards.
SBP frameworks: The State Bank's EMI and branchless banking regulations set capital requirements, fund safeguarding rules, audit obligations, and interoperability standards that protect users' funds across financial institutions.
Security measures: PINs, MPINs, biometric authentication, device binding, transaction alerts, and two-factor authentication for high-risk actions. Encryption keeps sensitive information secure in wallets. AI and machine learning will enhance fraud prevention in digital payments going forward.
Biometric verification: Biometric verification is mandatory for all digital wallet users in Pakistan as of late 2025. Biometric authentication enhances mobile wallet security significantly.
User best practices: Users should avoid sharing OTPs or MPINs to prevent fraud. Verify recipient details before large transfers. Avoid public Wi-Fi for transactions. Immediately block cards or wallets if a phone is lost.
Raast and privacy: Raast has reduced the need to share full bank details, lowering fraud exposure when sending to phone-number IDs via digital channels instead of sharing account numbers.
Remittance safety: When receiving funds from abroad via ACE Money Transfer or other providers, confirm official channels and avoid informal middlemen.
Different wallets win in different categories. Many Pakistanis sensibly keep two or three wallets plus a bank account. Here is how wallets work for specific personas:
| User Type | Recommended Wallets |
|---|---|
| Rural or cash heavy users | JazzCash, Easypaisa, Konnect |
| Students and first-time digital users | SadaPay, NayaPay, Zindigi |
| Freelancers and online earners | NayaPay, SadaPay, Finja |
| Existing big-bank customers | Alfa by Bank Alfalah, Konnect by HBL, Zindigi by JS Bank |
| SME owners | Finja Wallet, JazzCash Merchant, Easypaisa Merchant |
For international remittances into Pakistan, expatriates should consider ACE Money Transfer as a primary app to fund local wallets and bank accounts efficiently. It pairs seamlessly with any of the consumer wallets listed above.
Test at least two wallets, compare real-world fees over a month, and keep the one that best fits your daily bill payments, e commerce shopping, and cash access needs.
Adopt secure mobile wallets, combine them with low-cost remittance apps like ACE Money Transfer, and gradually reduce dependence on over-the-counter cash transactions. The shift from physical cash to digital is already here - the only question is which wallet you open first.
Disclaimer: This article is intended for general informational and educational purposes only and should not be construed as legal, regulatory, tax, business, or financial advice. While reasonable efforts have been made to ensure that all facts, figures, and data are accurate and valid as of the date of publication, no warranty or guarantee is given as to the ongoing completeness, accuracy, or currency of the information.
The content is based on information available at the time of publication. Regulations, government policies, market conditions, and service offerings may change over time and vary across jurisdictions and providers. As a result, some information may no longer be current or applicable. Readers should independently verify all information and consult qualified professional advisors before making any financial, legal, or business decisions.