ACE Money Transfer
ACE Money Transfer

29 Apr 2021
A bKash wallet is the leading Mobile Financial Services platform in Bangladesh, launched on 21 July 2011 as a joint venture between BRAC Bank and Money in Motion LLC. Since then, it has fundamentally changed how millions of Bangladeshis manage money - shifting everyday transactions from physical cash to a digital wallet accessed through a simple mobile phone. In this guide, you'll learn how to open, use, and fund a bKash wallet, including how to receive money from abroad via international remittance platforms like ACE Money Transfer.
Licensed by Bangladesh Bank, bKash enables financial inclusion by allowing digital financial management for unbanked and banked individuals alike. The platform handles daily payments, savings, bill settlements, and remittances for over 83 million verified customers. Its nationwide network spans more than 350,000 agents and 900,000 merchants, making it the dominant force in Bangladeshi mobile money. bKash helps reduce reliance on cash for transactions in Bangladesh, giving people a secure digital alternative whether they live in Dhaka or rural Sylhet.
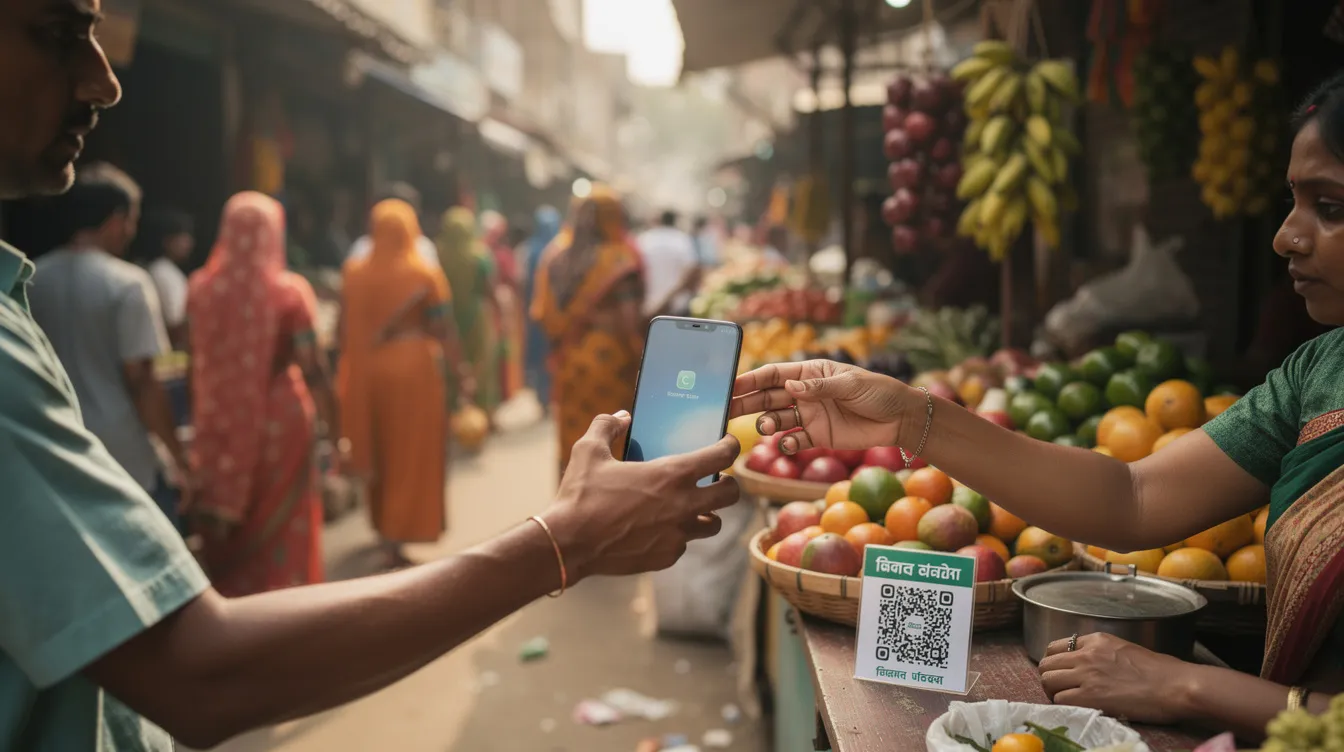
A bKash wallet is linked to a Bangladeshi mobile phone number and can be accessed 24/7 via a smartphone app or a USSD code (*247#). bKash supports both smartphone users and those using feature phones through USSD, so even without an internet connection, core services remain available. The bKash app provides real-time transaction history and summaries, giving users a clear display of their financial activity at any time.
All balances are maintained in Bangladeshi Taka (BDT), and bKash only settles payments in Bangladeshi Taka - there is no option to hold foreign currency. A bKash wallet allows users to store money using a mobile number, making transactions via bKash possible without a traditional checking or savings account. Here are the core functions:
Storing digital money in BDT on your device
Sending and receiving funds instantly between bKash accounts
Paying utility bills (electricity, gas, water, internet)
Mobile recharge for all major operators
Merchant payments via QR code scanning
Receiving international remittances
Accessing savings products and micro-loans
Converting digital balance to cash at agents or ATMs
Users can make digital payments and conduct financial transactions securely without a traditional bank account. bKash allows multiple digital transaction types including payments, money transfers, and bill payments - all from a single wallet tied to your mobile number.
Eligible individuals can open a bKash account for free with valid identification. Registering a bKash account uses the user's mobile number as an identifier, and you can set up your wallet in one of three ways:
Via the bKash app using e-KYC (electronic Know Your Customer)
At any authorized bKash agent point or digital registration center
At partner banks like BRAC Bank or customer care centers
Here is the required documentation and step-by-step activation flow:
Prepare a valid Bangladeshi National ID (NID), passport, or driving license, plus a mobile SIM registered in your own name.
Download the bKash app and tap "Login/Register." Enter your mobile operator and number, then verify via OTP.
Agree to the terms of service. Upload photos of your NID (front and back).
Take a selfie for face verification and submit.
Wait for verification via SMS - this can take up to 48 hours.
Once verified, create a 5-digit PIN within 72 hours. Your account remains inactive until this PIN is set.
New accounts are subject to daily and monthly transaction limits imposed by Bangladesh Bank regulations. For example, bKash-to-bank deposits may be capped at BDT 50,000 per day and BDT 300,000 per month. Always check the "Limit" section in your app for current figures.
The bKash system operates through a nationwide network of local retail agents and partner banks, giving users multiple ways to load funds. Users can load funds into their bKash wallet through local agents or bank transfers.
Cash In via agents: Visit any authorized agent with cash and your mobile number. The agent processes the deposit, and your balance is credited instantly. No bank account is required - agents act as "human ATMs" across the country.
Bank-to-wallet transfers: bKash integrates with 44 commercial banks. Link your bank account in the app to move money digitally. Fees vary by bank (typically around 1.00%–1.25% for bKash-to-bank; bank-to-wallet may be free or carry a small charge).
International remittances via ACE Money Transfer: Senders abroad can send funds directly to a recipient's bKash wallet. The sender flow works like this: create an online account on the ACE Money Transfer website, choose Bangladesh as the destination country, select Mobile Wallet as the payout option, enter the recipient's bKash wallet number, pay via debit card, credit card, or online bank transfer, and track the transfer using the reference number provided.
Manual wallet transfer mode: For certain integrations, manual wallet transfer mode requires only a bKash wallet number - no API keys are needed for manual wallet transfer mode. This simplifies receiving money from various platforms.
The Bangladesh government often provides a 2.5% incentive on remittances sent through official channels. Recipients can save on cash-out fees too - for instance, ATM remittance cash out is charged at just 0.70%.
bKash supports instant peer-to-peer money transfers between users. Sending BDT from one wallet to another takes seconds via the app or the *247# USSD menu.
Open the app, select "Send Money," enter the recipient's bKash number, and confirm the name that appears on screen. Enter the amount and your PIN to complete.
Recipients receive an SMS notification the moment money arrives. The balance is immediately active and usable for payments, purchases, or cash out.
Users can withdraw cash from agents and specific ATMs using their bKash wallet. At ATMs (BRAC Bank, City Bank, Q-Cash network), you generate a security code via the app, then enter it at the ATM along with your bKash number. ATM cash out fees apply (approximately BDT 14.90 per BDT 1,000).
Through Priyo Agents, cash-out charges drop to BDT 13.95 per BDT 1,000 for monthly withdrawals up to BDT 50,000. Beyond that threshold, the fee increases to BDT 18.50 per BDT 1,000.
Always verify the recipient's number and name on your screen before confirming. Never share your PIN during any transfer.
For example, sending money from Dhaka to a family member in Chattogram takes about 10 seconds - the recipient sees the funds immediately and can either spend them at a merchant or walk to the nearest agent to cash out.
The bKash app consolidates everyday payments into a single screen, making it easy to manage recurring expenses.
Utility bills: Navigate to "Pay Bill" in the app to pay electricity, gas, water, internet, and TV subscriptions. Select the biller, enter your customer ID, and confirm from your bKash balance.
Mobile recharge: Top up any major Bangladeshi operator - Grameenphone, Robi, Banglalink, or Teletalk - directly from the app or USSD. bKash integrates cashback and promotional discounts for users during special campaigns, so keep an eye on the banner notifications in the app.
Merchant payments: Users can pay at hundreds of thousands of merchants by scanning QR codes at supermarkets, pharmacies, restaurants, and online stores. Many e-commerce sites now display bKash as a checkout option, letting customers pay with their wallet balance instead of cash on delivery.
Developer integrations: For merchants using FluentCart, FluentCart must be installed to activate the bKash plugin. During checkout, customers enter wallet number, OTP, and PIN. bKash confirms payments through execute and query APIs, and a transaction is marked paid after bKash API reports completion. Transaction details are stored in FluentCart order records. Sandbox credentials for testing are available on bKash's developer portal, letting merchants test before going live.
Beyond transfers and payments, the bKash wallet offers financial products that were once out of reach for many Bangladeshis.
Digital savings: In partnership with banks, bKash lets users set aside small amounts into term deposits or recurring micro-savings. These preferences can be configured directly in the app under the "Savings" menu. Interest rates depend on the partner bank.
Nano loans and microcredit: Users with verified accounts and sufficient transaction history may qualify for small digital loans disbursed straight to their bKash wallet. Repayment terms and interest are governed by the partner lender, with Bangladesh Bank oversight.
Government and salary payments: Employers and government agencies use bKash for payroll disbursement and allowance payments, ensuring funds reach recipients without delay.
These services give traditionally excluded communities the ability to save and borrow responsibly, all from the same app they already love for daily transactions.
Keeping your bKash wallet secure comes down to a few consistent habits and an understanding of the platform's built-in safeguards.
Protect your PIN: Your 5-digit PIN is required for every transaction. Never share it with anyone - not agents, not callers claiming to be from bKash, not family. Change it immediately if you suspect any compromise.
Know your limits: Transaction and balance limits are set in order to comply with Bangladesh Bank regulations. Typical caps include BDT 25,000 per day for send money and BDT 200,000 per month. These figures can change, so check the "Limit" section in your app regularly.
Watch for fraud: Common issues include fake prize calls, phishing SMS asking for your PIN or OTP, and unofficial social media pages. bKash will never ask for your PIN via call or message.
Enable security features: Turn on biometric login (fingerprint or Face ID) in the app for eligible transactions. Use session time-outs and transaction alerts. bKash follows payment-card security standards, including PCI-DSS, to protect user data.
Use authorized agents only: For cash-in and cash-out, always verify the agent's credentials. Check the SMS confirmation and agent's name on your screen before leaving the counter. bKash only settles transactions in Bangladeshi Taka, so any request for foreign currency or off-platform payment is a red flag.
Following these practices keeps your money safe while you enjoy the convenience of managing your finances from anywhere. Whether you're handling daily expenses in Dhaka or receiving remittances from a family member abroad, the bKash wallet puts secure, 24/7 financial access in your hands. Download the app, create your account, and start using Bangladesh's most trusted mobile money platform today.